Nutrition & Fitness

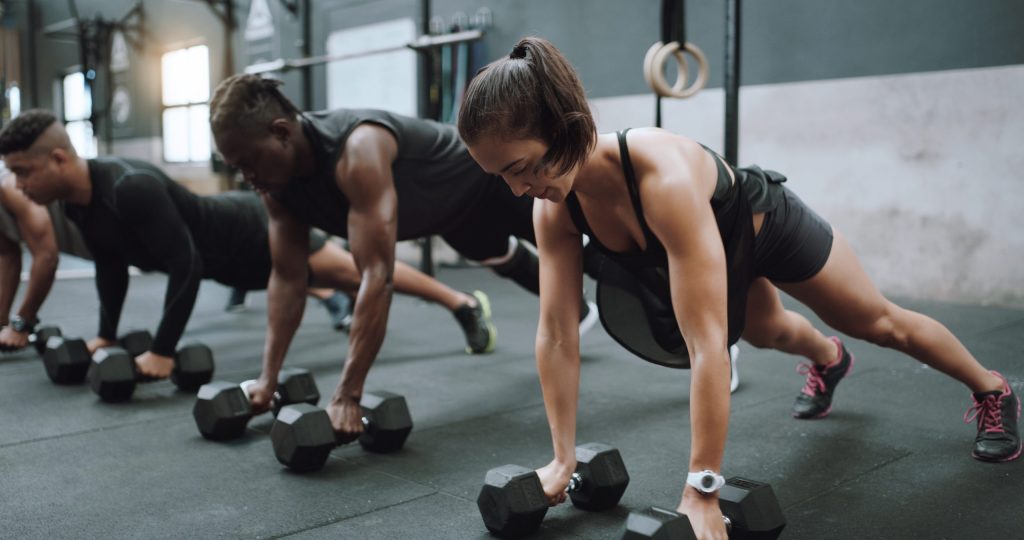
Nutrition and Fitness insurance is designed for gym owners, personal trainers, and wellness professionals promoting healthy lifestyles. With over 9,000 fitness and recreational sports centres in Canada, specialized coverage protects against client injury claims, equipment liability, and professional errors in dietary or training guidance. 

Nutrition and fitness businesses provide essential health and wellness services but are exposed to liability claims from clients, equipment damage, and operational interruptions. Personal trainers, gyms, studios, and wellness coaches may face injury claims, professional liability, and business interruptions that can impact both revenue and reputation.
Tailored insurance solutions from Oracle RMS for this industry protect assets, clients, and operations, enabling wellness professionals to focus on delivering safe,
high-quality services while minimizing risk and financial exposure.

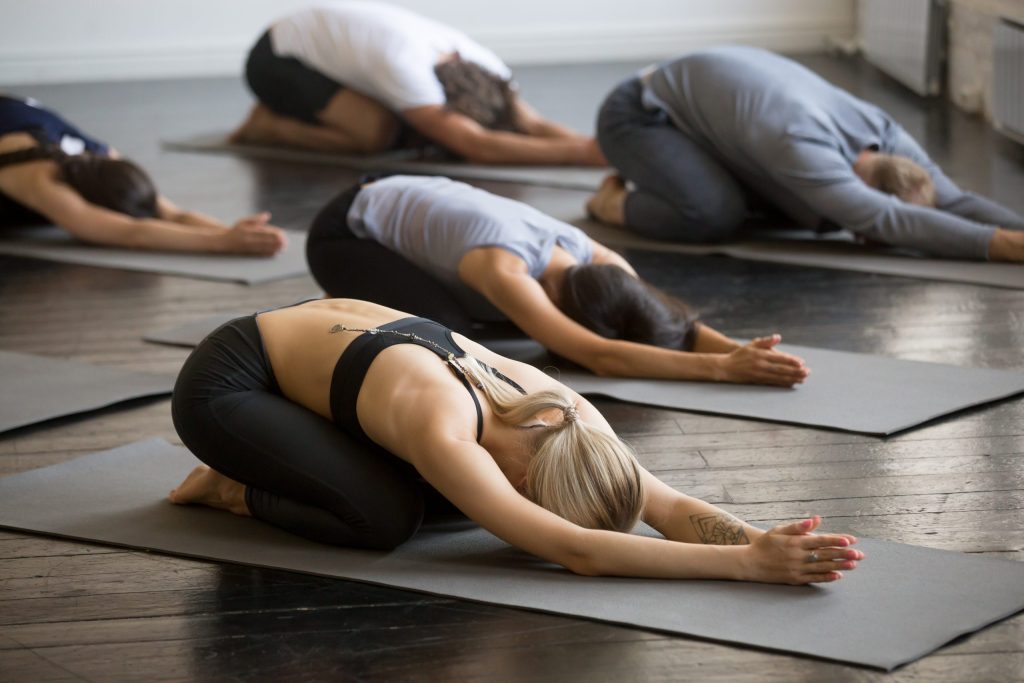
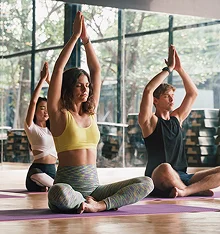
Oracle RMS website section for fitness key professions featuring a diverse group of people sitting cross-legged on yoga mats meditating with hands raised in prayer position.

Key Professions

  • Personal trainers 
  • Fitness studios 
  • Nutritionists 
  • Yoga and Pilates instructors 
  • Wellness coaches 
  • Sports performance trainers 
  • Online fitness professionals 

Key Coverages

Why Choose Oracle RMS

Oracle RMS helps fitness and wellness professionals stay protected while focusing on their clients. Call us or fill out a quote form to get started.

Frequently Asked Questions

What insurance does a gym, studio, or personal trainer need in Ontario?

Most fitness businesses carry commercial general liability covering participant injury, professional liability covering instruction and programming, commercial property for equipment and leasehold improvements, and business interruption. Facilities with employees should also review their obligations for staff coverage. Trainers, yoga and pilates instructors, nutrition coaches, and multi-location gyms each need different structures, and coverage can be arranged for independent professionals as well as full facilities.

Partly. General liability responds to premises-type claims, such as a client tripping on damaged flooring or being struck by falling equipment. Claims alleging that your program design, coaching, or supervision caused an injury are professional in nature and belong under professional liability. Because most fitness claims involve both elements, we recommend carrying both together rather than relying on general liability alone.

Yes. Advice-based claims, such as an eating plan that aggravated a medical condition or a failure to refer a client to a physician, are professional liability exposures and are not covered by general liability. In Ontario, dietitians are a regulated profession with college requirements, while nutrition coaching is not regulated the same way. Your broker will confirm your coverage aligns with your credentials and scope of practice.

No. Waivers are a valuable risk management tool and we recommend using them, but they are not a substitute for insurance. Waivers can be challenged, may not extend to every claimant, and generally do not prevent a claim from being brought, meaning you still face legal defence costs that your policy covers. Treat both as layers of the same protection.

Not automatically. Bootcamps in a public park, sessions in a client’s home, corporate wellness programs at an employer’s office, and online coaching each change your exposure and sometimes your policy territory. Municipal park permits often require proof of insurance with specific wording. Tell your broker where and how you deliver services so the policy reflects your actual operations.

Selling supplements, protein products, prepared meals, or branded equipment creates a product liability exposure separate from your service exposure. This applies whether you manufacture the product, private-label it, or simply resell it at your front desk. Let your broker know about any retail component so products and completed operations coverage is included.

Commercial property coverage protects owned equipment, leasehold improvements, and contents against fire, theft, and water damage. Confirm whether equipment is valued at replacement cost or depreciated value, and whether damage caused by member misuse is covered, since abuse and misuse are commonly excluded. Leased or financed equipment may also carry specific insurance obligations under the finance agreement.

Industry